In the dynamic world of emerging-market fintech, achieving lasting global scale requires disciplined operational execution, prudent credit management, and a deep understanding of local market realities.
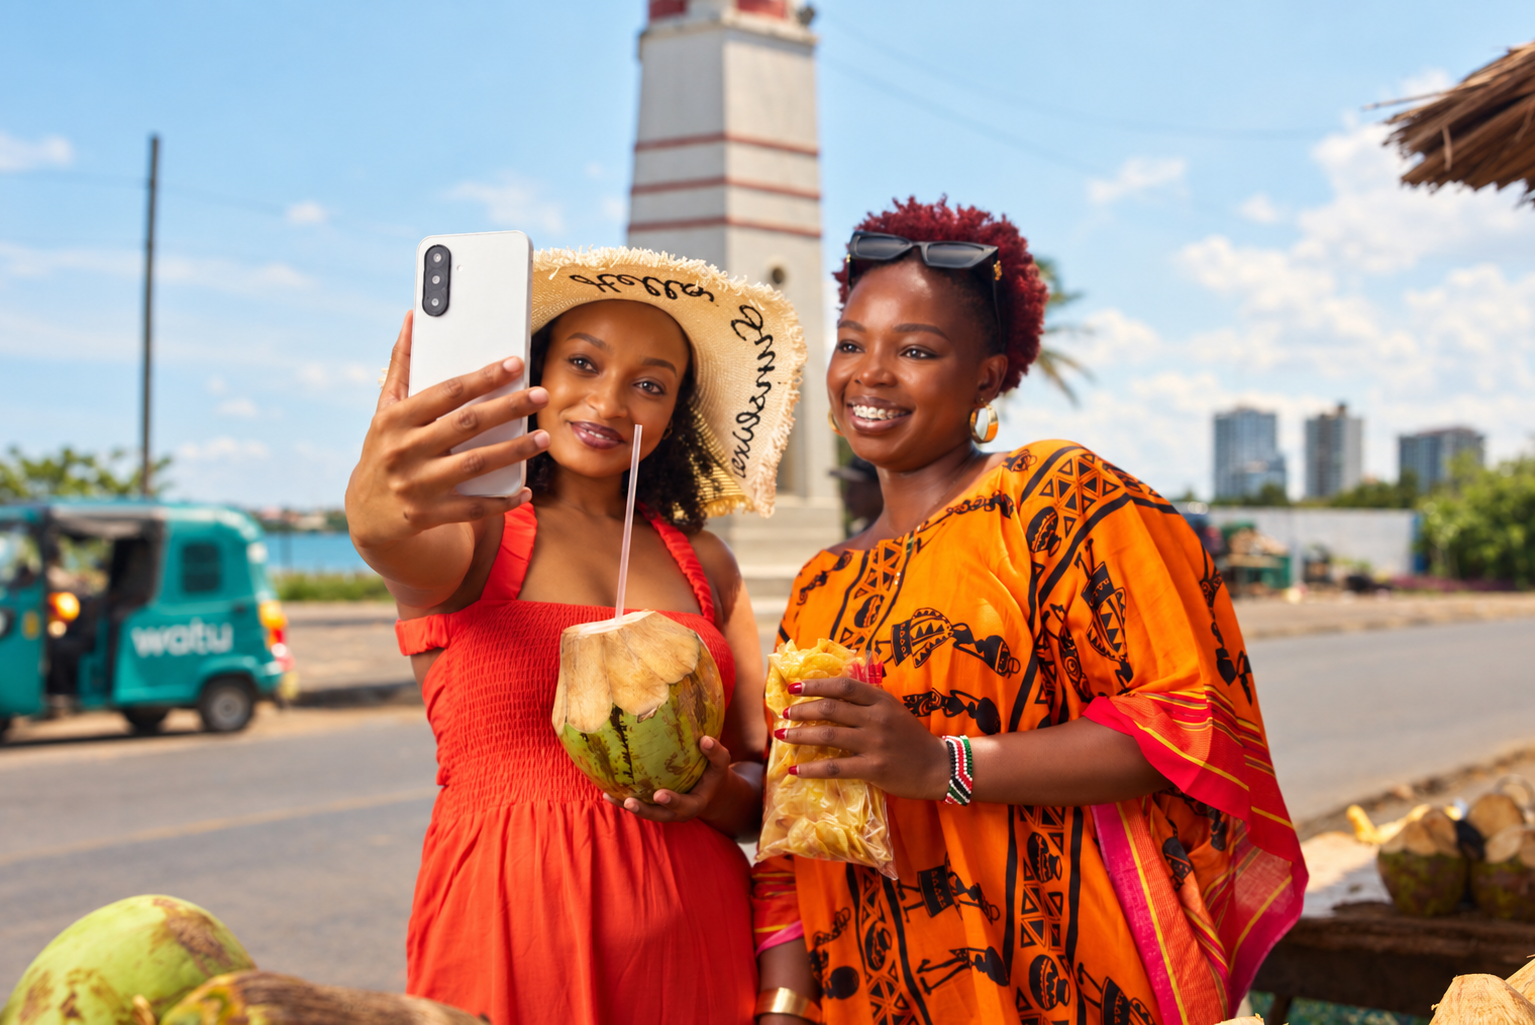
Watu’s multi-market trajectory exemplifies this principled approach to sustainable expansion. The company started in Mombasa, Kenya, in 2015, financing motorcycles for boda riders on the coast. Ten years on, the productive asset finance platform operates across eight African markets, including Nigeria, Uganda, Rwanda, and South Africa, and two Latin American markets, Brazil and Mexico. The company has unlocked more than $1.8 billion in credit and impacted over 15 million lives, financing assets that customers use to earn their income.
Yet, what captures institutional attention is not merely the geographic footprint; it is the capital discipline that funded its early trajectory. Watu scaled into a market leader without relying on early equity dilution.
When investor Paras Patel—then running a sizeable venture capital fund—first met Watu Founder and CEO Andris Kaneps in 2020, he was evaluating thousands of startups across the continent. Patel recalls being struck by two immediate operational facts: the sheer velocity of Watu’s growth, and the total absence of traditional venture equity on its cap table.
“Normally, it takes me one or two weeks to make the decision to invest,” recalls Patel, who today serves as Co-CEO alongside Founder Andris Kaneps. “But within the first half-hour, I was like, Okay, Andris, how can I invest?”
How did an asset-finance business scale across complex, multi-jurisdictional emerging markets while preserving capital discipline? The answer lies in an institutional framework built around four core operational pillars: a strict methodology of piloting, a localized “champion” leadership model, deep regulatory alignment, and rigorous capital controls.
The Mechanics of Controlled Expansion: Test, Prove, Scale
Unlike platforms that deploy capital ahead of proven unit economics, Watu’s cross-border expansion relies on a phased, risk-mitigated entry strategy.
Before allocating balance sheet capital to a new market, Watu enters what Paras terms “learning pilot mode.” Instead of commissioning months of external management consulting reports, the executive team sets up small, closely monitored operational tests.
“We would rather run a small test than commission six months of analysis,” says Paras. “Does it meet the criteria we care about? Then we go in small, and we learn from real customers instead of a slide.”
This approach keeps capital commitments low until credit risk, repayment behaviour, and local market nuances are thoroughly stress-tested.
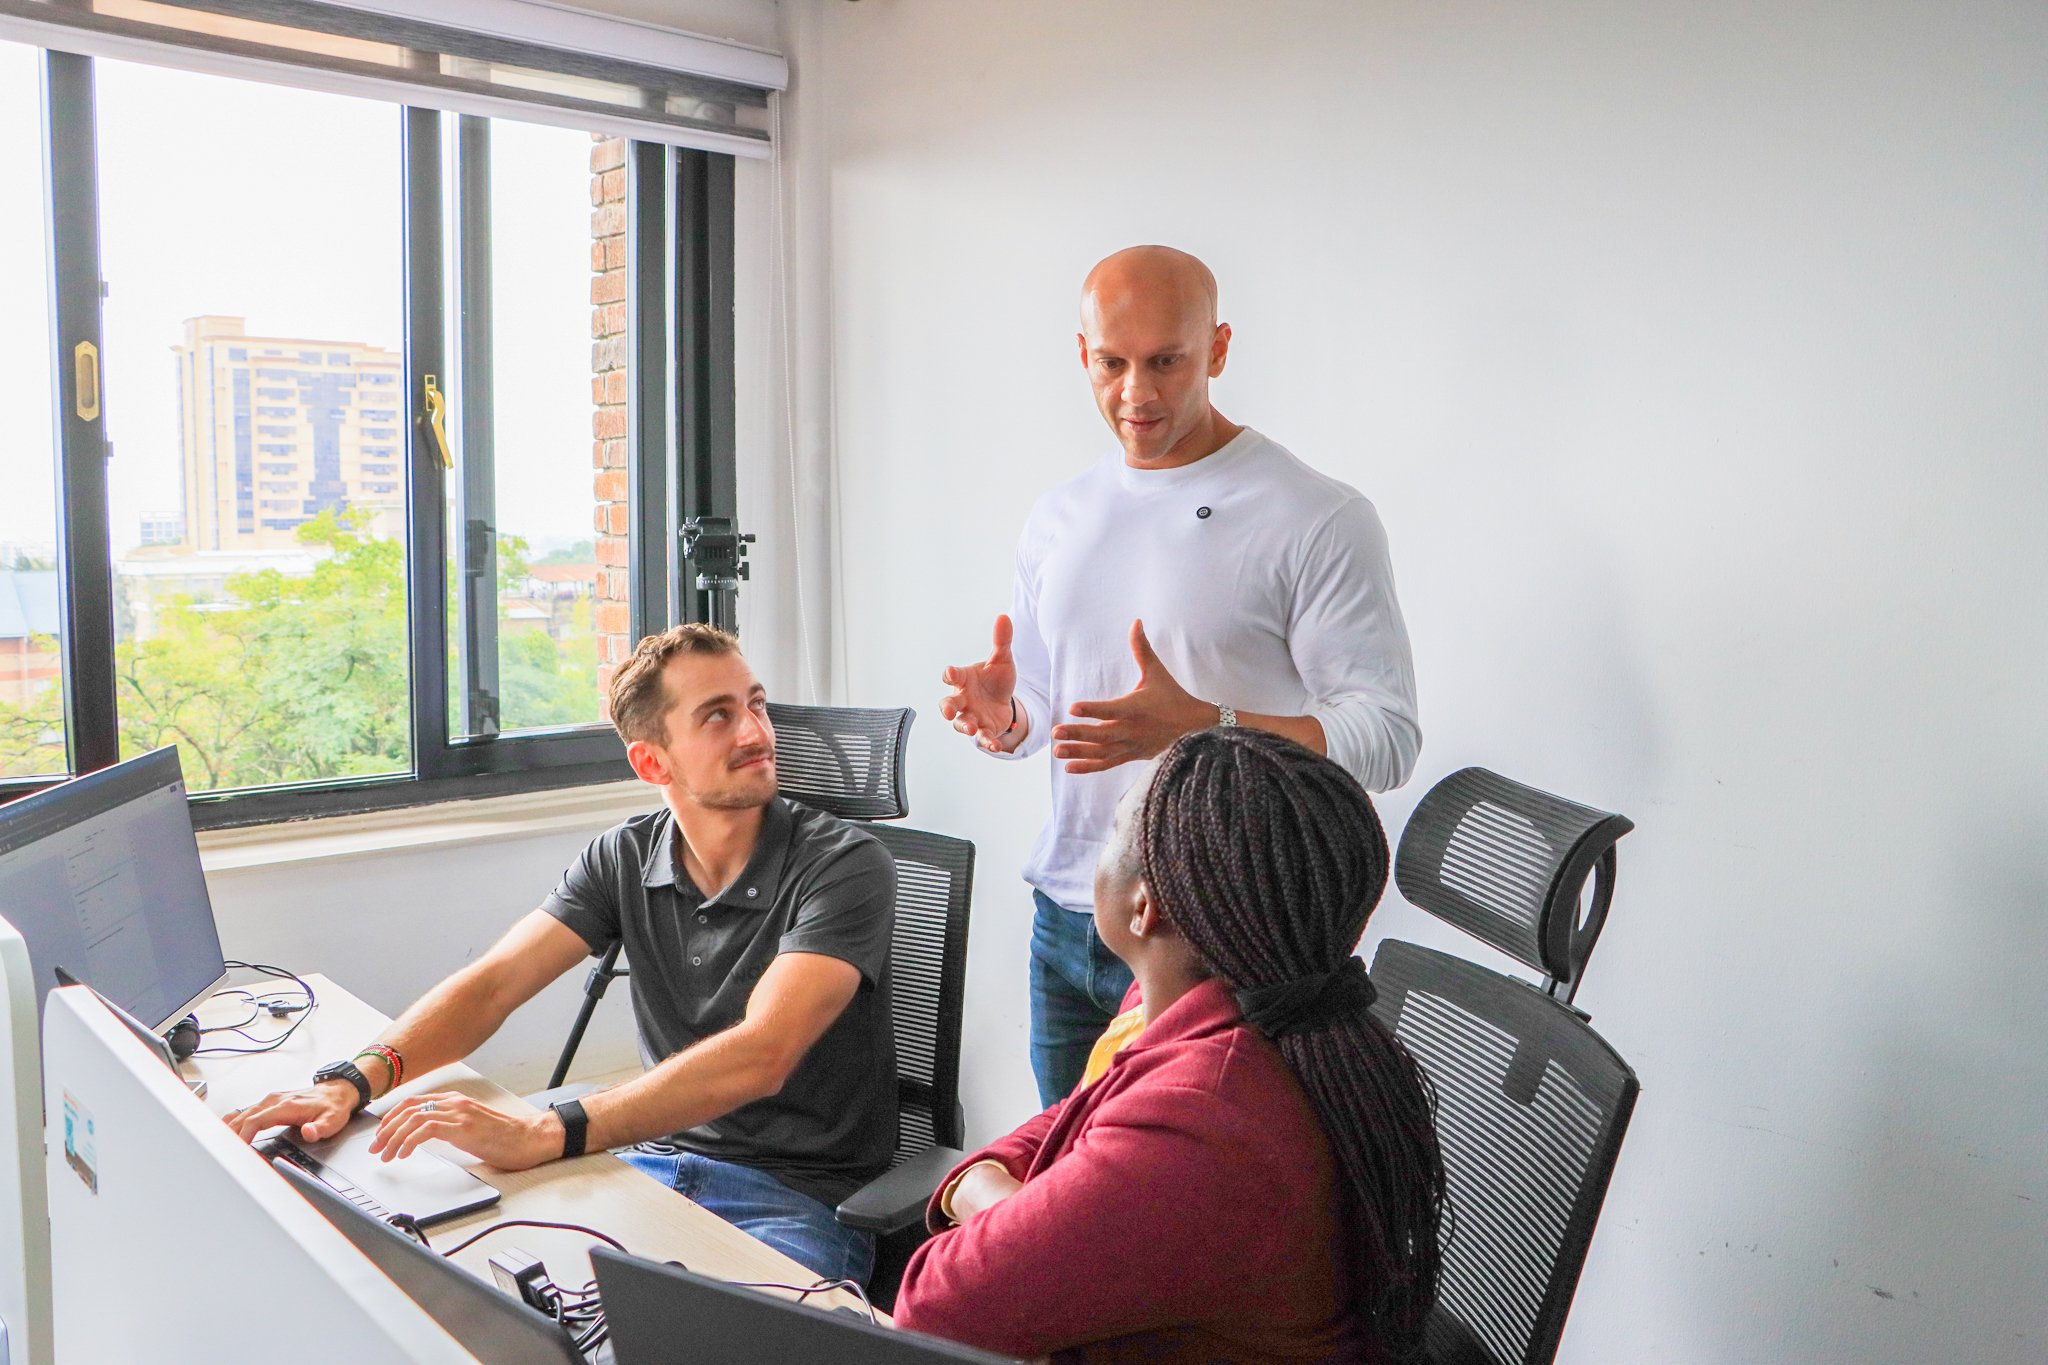
“When we start out in a new country, or with a new product, or a new idea, we treat it as a small startup,” Kaneps explains. “It starts with a little test—100 customers, 1,000, maybe 10,000. We don’t believe in this approach of ‘let’s throw in money, let’s get a huge number of clients,’ only to find out that the business model itself isn’t sustainable. Our approach is the opposite. We start small, properly test the business model and its commercial viability, and only when we are confident, that’s when we scale it up.”
This controlled rollout has kept Watu clear of the collapses that have hit other well-funded lenders. As Paras notes, subsidised rates can carry a business a long way while capital is cheap. When capital tightens, the model has to stand on its own economics, and customers are left with stranded assets when it does not.
In-Country Leadership: The “Champion” Model
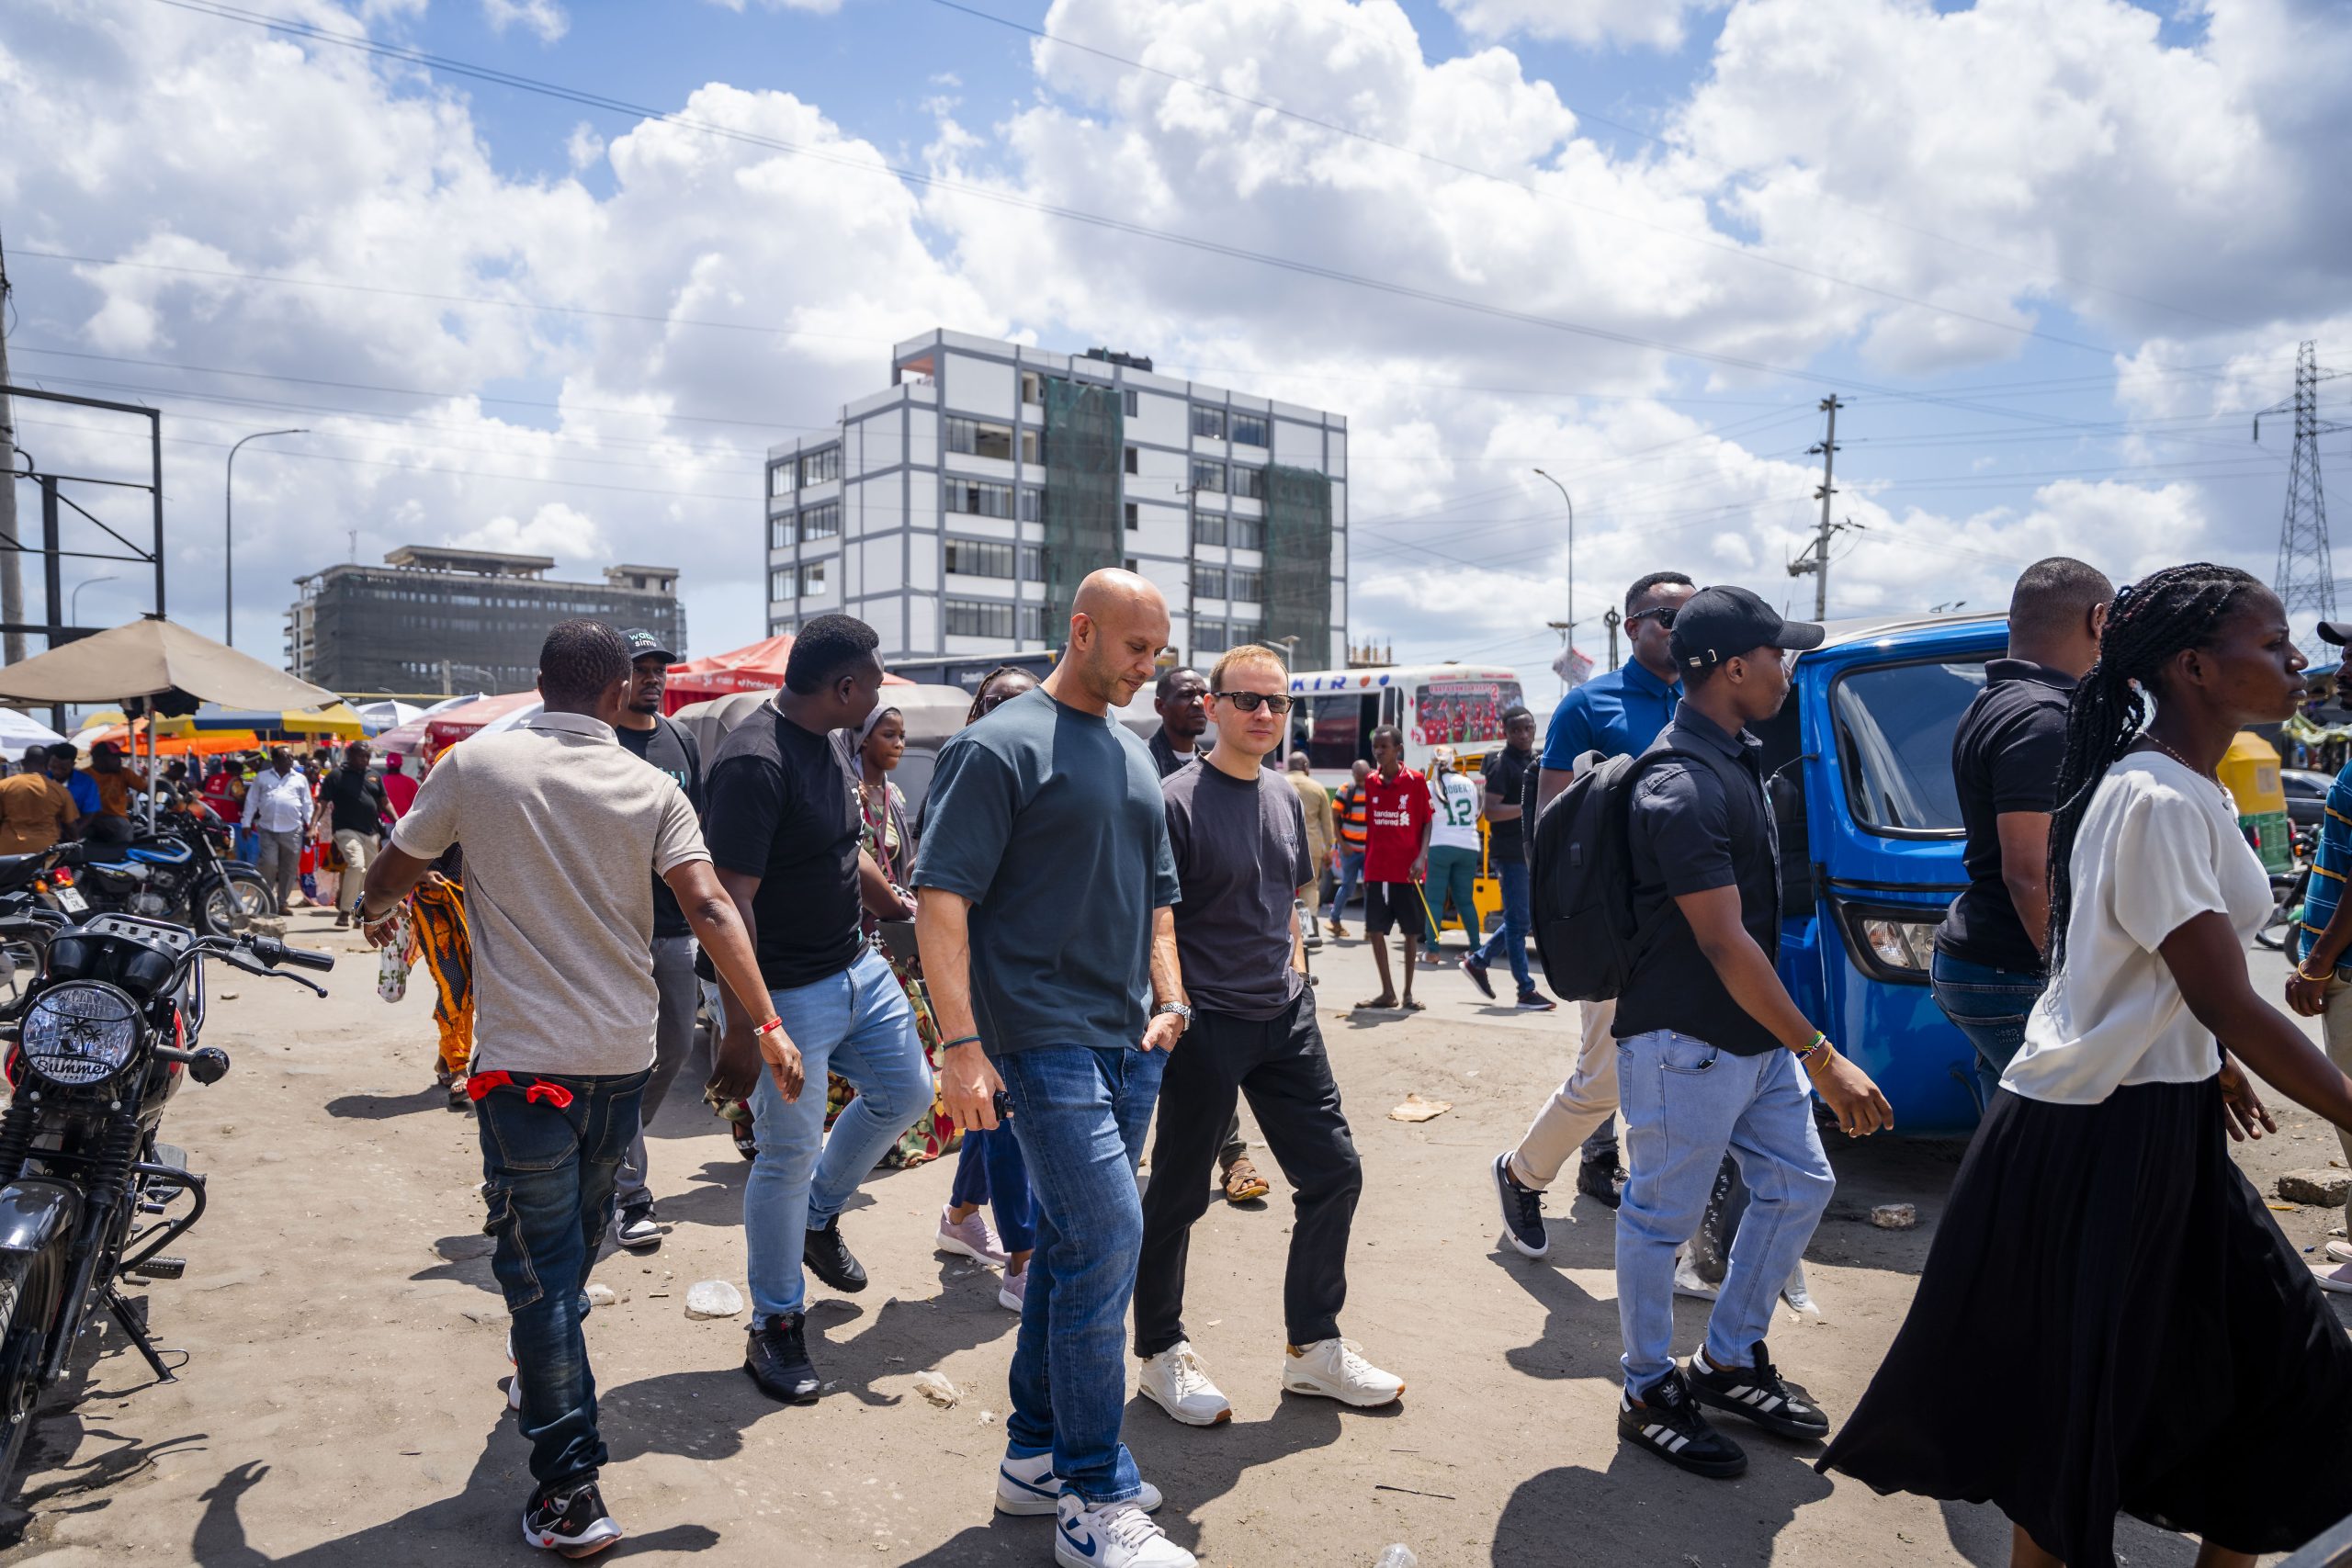
Operating in ten regulatory and cultural environments requires local execution. Kenya, Nigeria, and Rwanda differ sharply in distribution channels, consumer behaviour and operating constraints.
To manage this complexity without creating an over-centralised corporate structure, Watu relies on country-level “champions”—local operational leaders who possess deep regional expertise and an entrepreneurial mandate.
“We do not run Sierra Leone from a head office in Nairobi,” Paras notes. “Each market has its own channels, its own dealers, its own pace. So we look for people who take the Watu model, keep what travels, and change what does not. They know things we never will.”
These local leaders are backed by centralised technology and risk-scoring systems, but retain the autonomy needed to navigate regional distribution nuances, ensure regulatory compliance, build local dealer networks, and manage field-level operations.
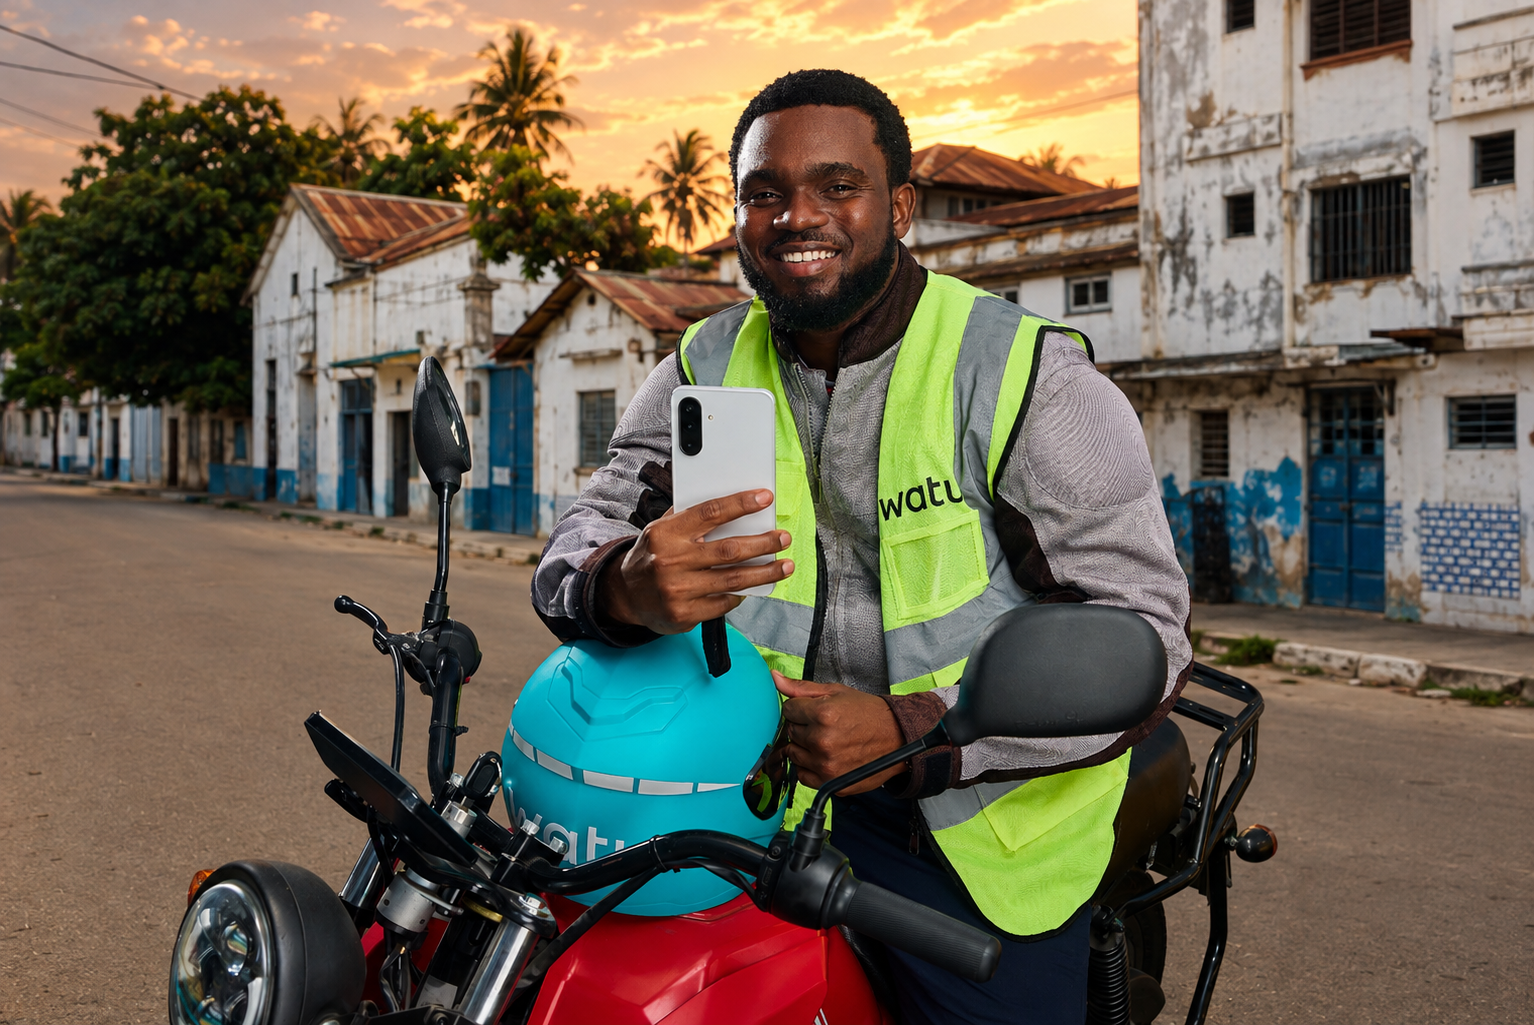
Navigating Regulatory Frameworks and Monetary Controls
In cross-border asset financing, regulatory compliance and foreign exchange (FX) management represent critical risk vectors. Expanding from East Africa into major markets like Nigeria, South Africa, Brazil and Mexico requires active alignment with varying central bank mandates, interest rate caps, and currency repatriation frameworks.
Watu addresses these requirements through a structured legal and financial review before scaling beyond the pilot phase. “First, licensing. Licensing and regulatory compliance are fundamental considerations in our market-entry decisions, alongside the commercial viability of each market,” Paras emphasises. “If the maths does not hold for the customer and for us, the market is not ready for our model yet, and that is our constraint, not the regulators.”
Equally critical is capital structure management. As a global firm attracting balance sheet funding from international institutions, Development Finance Institutions (DFIs), and specialised credit funds, Watu must navigate complex foreign exchange dynamics.
“When we start in a country, we often fund initial operations through our own balance sheet equity, moving hard currency into the market,” Paras explains. “Understanding local FX controls and capital mobility is vital, because we are bringing money in and we need to know how it behaves. In some markets, liquidity management is harder. We need to fully understand the environment before committing to a long-term scale.”
By maintaining full compliance and structuring localised debt facilities—such as subordinated local-currency debt instruments raised in key markets—Watu hedges against currency depreciation while maintaining capital efficiency.
One Model, Many Markets
While legal frameworks vary, the core economic problem Watu addresses is universal across emerging markets: hundreds of millions of economically active individuals working in informal sectors lack the traditional collateral required to access productive assets.
 Whether a motorcycle driver in Kenya, an electric bike operator in Rwanda, or an accountant from Nigeria using a financed smartphone to generate reports, the fundamental economic driver remains unchanged. By pairing smart asset tracking—such as phone-locking technology and remote telematics—with lease-to-own financing, Watu turns the asset itself into primary collateral.
The Institutional Outlook
Watu’s evolution from a coastal Kenyan business into an international asset finance platform offers a template for growth in markets that traditional lenders have priced out. By maintaining underwriting discipline rather than chasing customer acquisition, relying on local operational leadership, and keeping strict regulatory alignment, Watu has built a business that stands on its own economics. The impact follows from that, rather than justifying it.
As Watu deepens its footprint across Africa and Latin America, and continues to expand into electric mobility and digital connectivity, its focus remains clear: building financial infrastructure that works commercially and can be repeated market by market.